



Ethena’s USDe, an artificial greenback concentrating on $1, has 51.2% of its backing allotted to DeFi and institutional lending, based on danger assessor LlamaRisk’s October 12 evaluation. The allocation determine doesn’t measure precise borrower drawdowns or money accessible for rapid withdrawal. For holders, usable reserve belongings and entry to an exit close to the peg are separate checks.
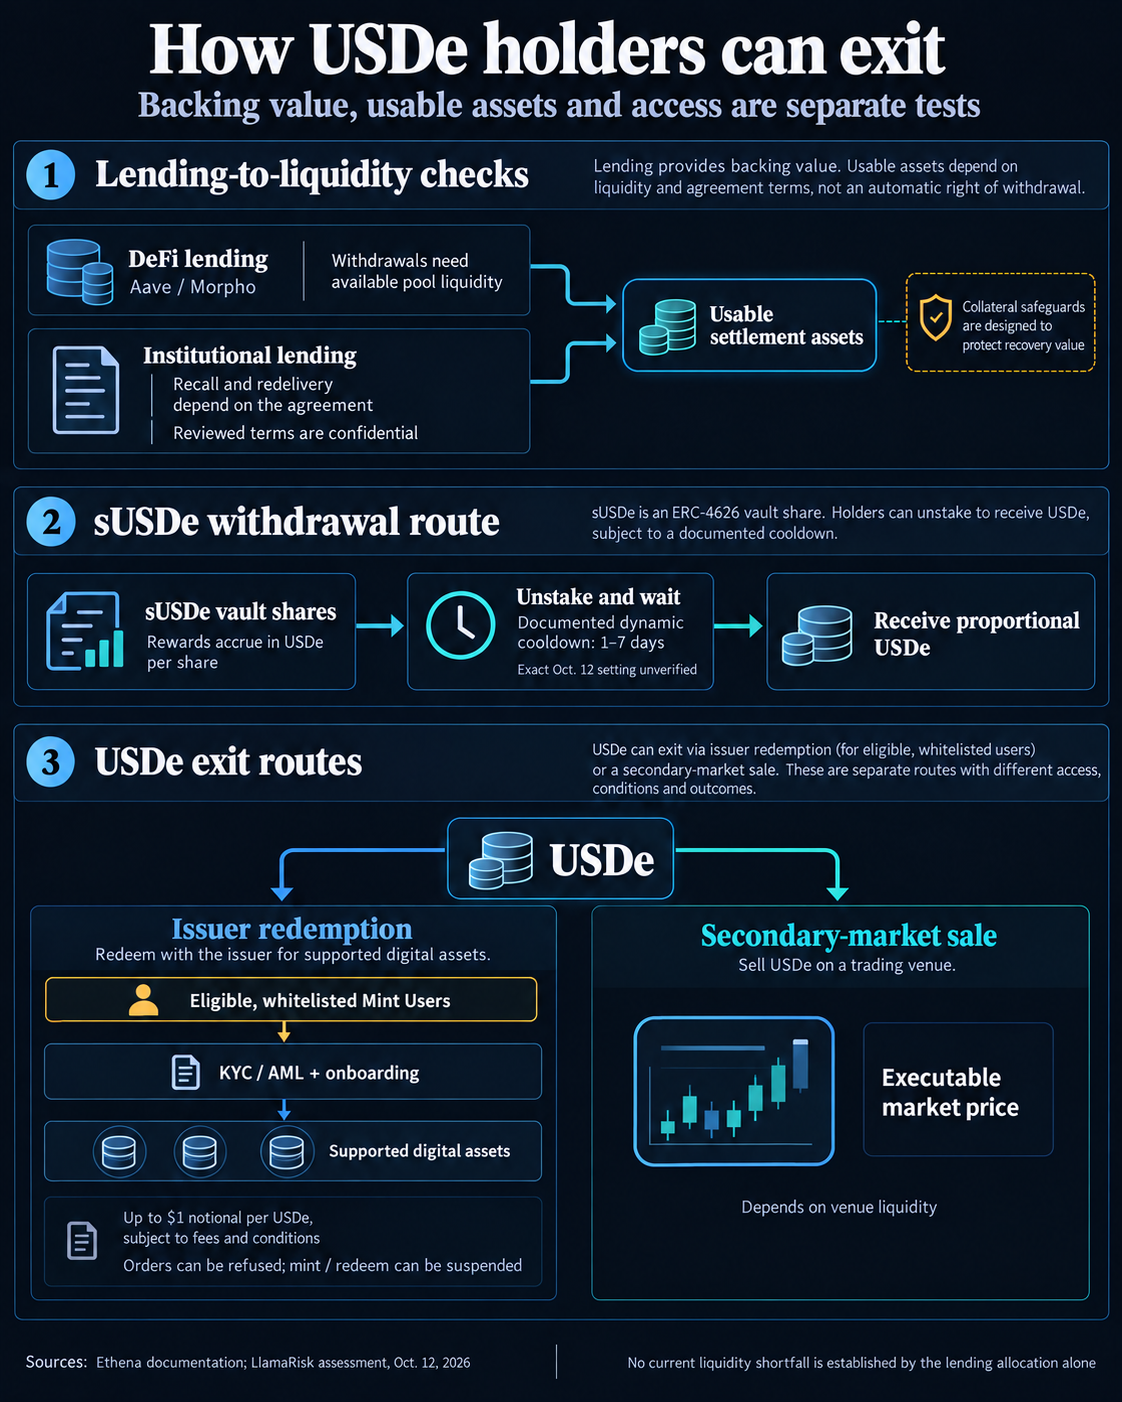
Eligible counterparties can redeem USDe straight with Ethena, topic to its situations. Different holders depend on secondary markets for an exit. Withdrawing USDe from sUSDe, its staking vault share, requires a separate unstaking course of. A lending place can have extra collateral whereas provided stablecoins stay borrowed. Recovering these belongings is dependent upon accessible pool liquidity or the relevant mortgage settlement’s recall and redelivery provisions.
The worldwide snapshot stories $4.76 billion of backing in opposition to 4.76 billion USDe excellent. Its lending allocations are 36.9% DeFi and 14.3% institutional, alongside 24.9% liquid stablecoins, 17.6% crypto foundation and 6.0% real-world belongings.
LlamaRisk discloses partial Aave DAO funding and its unbiased Ethena proof-of-reserves attestation position. It says it acquired no protocol or affiliated-entity compensation for this evaluation.
The diversification itself predates this snapshot. Ethena’s March governance discussions already described lending deployments, and CryptoSlate lined the broader backing shift in August.
Standard Chartered says Ethena's ENA could crush Bitcoin and Ethereum returns by 2028
When lending belongings turn into redemption belongings
Ethena’s DeFi lending coverage describes reviewed markets with extra borrower collateral, conservative loan-to-value parameters and publicity limits topic to governance and Danger Committee overview. These safeguards goal to restrict losses. Aave and Morpho’s withdrawal mechanics decide whether or not underlying belongings can be found to recuperate.
Underneath Aave’s withdrawal guidelines, a provider can take out solely the quantity accessible in a pool that has not been borrowed. Morpho’s market design additionally makes adequate liquidity a situation for withdrawal.
| Lending class | Share of backing, Oct. 12 | Route again to settlement belongings |
|---|---|---|
| DeFi lending | 36.9% | Withdraw provided belongings, topic to accessible market liquidity. |
| Institutional lending | 14.3% | Get well lent belongings beneath the relevant settlement’s recall and redelivery provisions. |
For institutional lending, Ethena describes stable-asset loans backed by collateral price greater than the quantity borrowed, together with liquid BTC and ETH. Certified custody and triparty preparations, through which an unbiased agent holds and administers collateral, are designed to guard the protocol’s declare. Counterparty eligibility and mixture publicity limits are topic to committee oversight.
LlamaRisk’s April overview framework examines collateral ratios, custody segregation, enforceable safety pursuits, liquidation rights, recall discover and redelivery timeframes. On Ethena Governance, its March overview of the Maple and Anchorage agreements discovered no materials contractual deficiencies. The person phrases and industrial thresholds stay confidential.
The Anchorage settlement reviewed in March was with A1, Ltd., a Cayman Islands group entity distinct from the OCC-chartered Anchorage Digital Financial institution. Maple’s settlement was by means of Delaware-based Protocol Pool Operations Alpha LLC.
The collateral, custody and authorized safeguards are supposed to mitigate credit score danger. Their public descriptions don’t set up the precise timetable for recovering lent belongings beneath the reviewed institutional agreements. For a holder’s exit, safety of restoration worth and the timing of supply subsequently should be assessed collectively.
Aave’s $50 million lending plan could lose money without a single default
USDe redemption and sUSDe withdrawals
Holding USDe doesn’t robotically present entry to Ethena’s main redemption facility. Its printed phrases reserve that service for eligible Mint Customers who’ve accomplished know-your-customer and anti-money-laundering checks, different onboarding procedures and whitelisting. An peculiar holder must turn into an eligible Mint Person to redeem straight, or use a secondary-market exit.
The phrases describe conditional redemption into supported digital belongings representing a pro-rata portion of reserves, capped at $1 in notional worth per USDe and topic to charges and different situations. Receiving a backing asset is a unique step from receiving {dollars} in a checking account. Ethena’s order course of makes use of signed costs and operational acceptance checks, so a nominal redemption framework doesn’t make each requested order executable.
LlamaRisk’s October 12 evaluation of the Ethereum contract lists PYUSD, USDC, USDG, USDT, USDm and USDtb as enabled stablecoins, plus DAI with smaller limits. It stories an mixture redemption ceiling of 20 million USDe per block, in opposition to 200 million for minting, and a pair of million in every path for DAI. These are contract ceilings, not accessible money. The issuer can droop minting and redemption with out the controller’s 24-hour wait.
This entry is central to Ethena’s peg-arbitrage mechanism. A certified participant can purchase USDe at a reduction on an exterior market and redeem it for backing belongings. The motivation to shut that hole is dependent upon having the ability to get hold of a usable quote and obtain the belongings. Secondary-market sellers depend on that arbitrage channel, in addition to the liquidity of the venue the place they promote.
sUSDe provides one other stage. It’s an ERC-4626 vault share, representing a proportional declare on USDe within the staking contract. Rewards enhance the USDe represented by every share. Its related trade price is USDe per share, slightly than a hard and fast $1 goal for sUSDe itself.
Ethena’s present staking steering describes a governance-set dynamic cooldown between one and 7 days. Its technical documentation locations pending unstaked USDe in USDeSilo earlier than withdrawal. The information provides a spread slightly than establishing the lively October 12 setting. Finishing that course of delivers USDe; promoting or redeeming that USDe is an additional step, with its personal liquidity and eligibility situations.
The reserve buffer and the checks that matter
Ethena’s reserve fund is meant to soak up unfavorable protocol income and backing shortfalls. LlamaRisk’s September evaluation put it at about $62.1 million. A loss buffer serves a unique goal from belongings prepared for rapid settlement.
Ethena’s reserve-fund coverage says its ongoing allocation of protocol income is 0%, with income directed as a substitute to incentives and promotional distributions. That allocation applies to new income; the fund’s current stability is a separate measurement.
September’s place mapping recognized Aave, Morpho, Jupiter Lend and Kamino exposures, alongside Maple, FalconX, Kraken, CBAM and Anchorage institutional positions. These detailed venue weights stay historic.
Blockworks Advisory’s March cooldown evaluation makes the liquidity-accounting distinction express. It separates withdrawable lending positions from these constrained by utilization, and explains that biking USDtb already held as USDe backing by means of USDe minting and redemption creates no internet liquidity.
Some Aave loans sit near liquidation with collateral that can take hours to cash out
Ethena’s institutional-lending coverage describes committee-reviewed limits with out specifying a numerical cap or ground.
For holders, the observable lending take a look at is accessible unborrowed liquidity alongside the quantity provided to every market. Institutional recall and redelivery disclosures want to take a seat alongside collateral high quality. A collateralized place and a place that may ship settlement belongings on demand reply completely different questions.
Redemption eligibility, accepted orders and the lively sUSDe cooldown full the exit take a look at.
The publish Greater than half of Ethena’s USDe backing is allotted to lending appeared first on CryptoSlate.