



France’s proposed crypto tax adjustments would make a transfer from Bitcoin or Ether into sure stablecoins a taxable disposal, even when the investor by no means withdraws money.
The Nationwide Meeting’s Finance Committee adopted modification I-CF1826 on Oct. 7, including that proposed exception to a broader overhaul of how non-public crypto positive factors are calculated. The availability would apply to disposals and exchanges from Jan. 1, 2027 if enacted.
For an investor promoting Bitcoin publicity into USDC, the consequence could be a change within the tax timing of a risk-reduction commerce. A acquire might turn out to be reportable whereas the proceeds stay in a crypto pockets or alternate account. However the proposal additionally adjustments the price deducted from these proceeds, and offers older holdings a transition selection.
Below French tax authority steering, lined crypto-to-crypto exchanges and not using a money balancing fee obtain tax deferral. Changing into fiat or utilizing crypto to acquire different items or companies can already be taxable beneath the private-disposal regime, topic to its relevant exemption.
CF1826 would take away the alternate deferral when the investor receives e-money tokens as outlined by the EU’s Markets in Crypto-Belongings regulation, or associated rights. The operative wording targets the asset acquired. A swap out of Bitcoin right into a qualifying token might subsequently acknowledge a acquire earlier than any later money withdrawal.
MiCA’s definition describes a crypto-asset that seeks to keep up secure worth by reference to at least one official forex. That authorized definition units the exception’s scope. The modification invokes it with out an categorical issuer-licensing situation.
ESMA proposes ending EU custody and transfer services for non-compliant stablecoins
USDC offers a concrete instance: Circle’s European white paper identifies it as an e-money token beneath the identical MiCA provision. The illustrations under use native USDC, with transactions measured in euros.
The modification’s sponsors justify the change by describing deferral on fiat-backed stablecoin conversions as a legislative loophole. For an investor utilizing a swap to cut back market publicity, the sensible impact could be earlier recognition of any acquire.
The proposed tax calculation issues the acquire above price. It subtracts the acquisition foundation of the belongings surrendered from the disposal value. That foundation is the price acknowledged for tax functions; a transaction can produce a acquire, no acquire or a loss.
Senate tax bill frees stablecoin spending while Bitcoin stays on IRS forms
Two methods to worth older holdings
France’s current portfolio-based calculation allocates a part of the acquisition value of your complete crypto portfolio to every taxable disposal. Present steering deducts complete portfolio acquisition value multiplied by the ratio of disposal value to portfolio worth instantly earlier than the transaction.
The proposed alternative would give attention to the crypto-assets truly disposed of. For belongings of the identical nature bought at completely different costs, it specifies weighted-average acquisition worth.
For holdings acquired earlier than 2027, the modification presents two routes. An investor might use evidenced precise acquisition prices, decided beneath the brand new foundation guidelines. Alternatively, the investor might allocate the portfolio acquisition value calculated beneath the outdated guidelines at Dec. 31, 2026 among the many belongings held then, in proportion to their values on that date.
The allocation choice preserves a pool of acquisition price and distributes it amongst holdings. The obtainable price pool stays the acquisition value calculated beneath the outdated guidelines, somewhat than the portfolio’s full market worth. The textual content makes that selection irrevocable for your complete portfolio when the primary return reporting a taxable disposal after Jan. 1, 2027 is filed.
Think about a hypothetical investor whose Bitcoin price €20,000 and is price €60,000, whereas their Ether price €40,000 and is price €40,000 on the transition date. The portfolio has €60,000 of acquisition price and a €100,000 worth. Assume no prior disposals, charges or money balancing funds, no different holdings of the identical tokens, and unchanged euro values via the transactions.
Below the allocation choice, Bitcoin represents 60% of the portfolio worth and receives €36,000 of foundation. Ether receives the remaining €24,000. Utilizing precise prices as a substitute would depart their bases at €20,000 and €40,000, respectively.
The identical Bitcoin-to-USDC transaction would then produce completely different first-disposal positive factors:
| Hypothetical transaction or foundation | Proposed actual-cost route | Proposed allocation route |
|---|---|---|
| Bitcoin foundation earlier than the swap | €20,000 | €36,000 |
| Acquire on swap into €60,000 of native USDC | €40,000 | €24,000 |
| Foundation of the USDC acquired | €60,000 | €60,000 |
| Acquire on later Ether disposal for €40,000 | €0 | €16,000 |
The desk compares hypothetical gross positive factors beneath the proposal. Below the present guidelines, the qualifying swap itself would obtain deferral. Below both proposed transition route, the Bitcoin-to-USDC swap would turn out to be a taxable occasion.
Altering solely the historic prices to €50,000 for Bitcoin and €10,000 for Ether reverses the first-disposal comparability: precise price would produce a €10,000 Bitcoin acquire in opposition to allocation’s €24,000. The remaining Ether acquire at unchanged values could be €30,000 beneath precise price or €16,000 beneath allocation. Historic prices decide which methodology acknowledges extra acquire first.
Foundation resets and the price of loss timing
The proposal expressly distinguishes exchanges that retain deferral from exchanges that turn out to be taxable. A deferred alternate carries the surrendered belongings’ foundation into the belongings acquired. A taxable alternate provides the acquired crypto-assets a foundation based mostly on the consideration worth already used to calculate the acquire, adjusted for any money balancing fee.
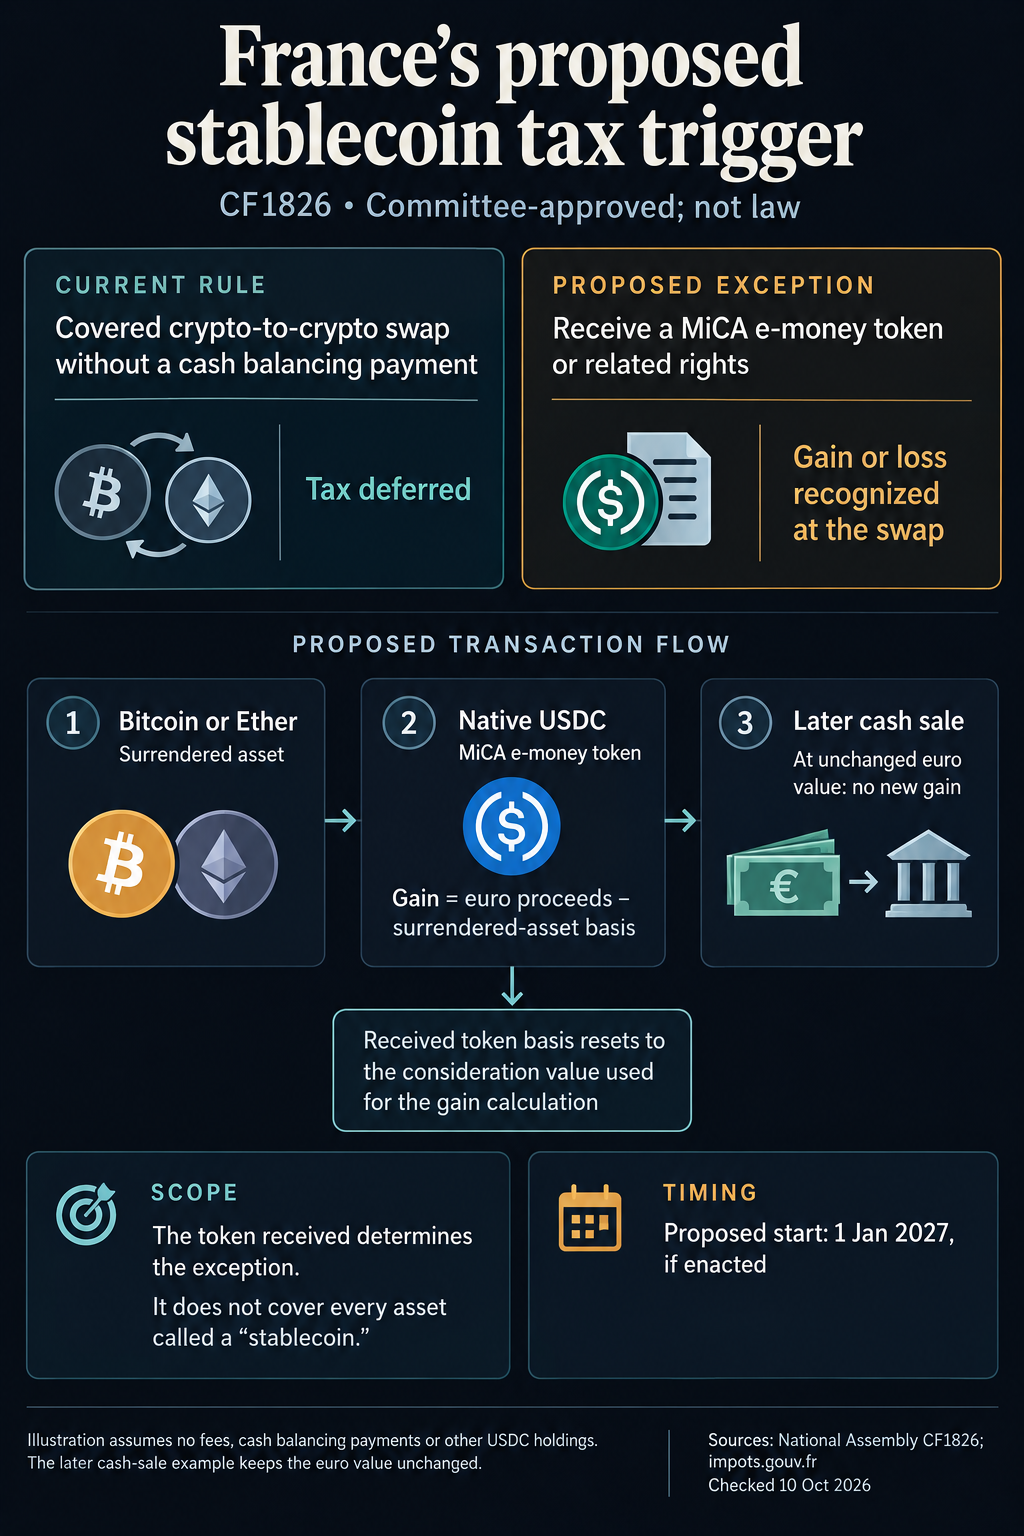
For the Bitcoin-to-USDC swap within the first instance, the reset rule would give the USDC acquired €60,000 of foundation beneath both transition route. Promoting it later for a similar €60,000 would produce no additional acquire. That reset would stop repeat recognition of the unique Bitcoin acquire when the unchanged-value proceeds lastly reached a checking account.
USDC references the greenback, so the unchanged-euro-value assumption is crucial. A later disposal at a unique euro worth would require its personal acquire or loss calculation.
Circle can delay European USDC redemptions if reserves cannot cross borders
If the investor additionally offered the remaining Ether for €40,000, the primary instance would produce mixture realized positive factors of €40,000 beneath both proposed transition route. Precise price acknowledges all of that in Bitcoin; allocation splits it between Bitcoin and Ether.
The modification would change the swap exception and foundation guidelines with out rewriting the present crypto loss restriction. The tax authority says crypto positive factors and losses offset throughout the similar tax yr, whereas a internet crypto loss can’t be carried into later years or used in opposition to positive factors on different belongings.
A separate hypothetical reveals the impact of recognizing losses and positive factors in several years. Below the proposed actual-basis guidelines, a sole Bitcoin holding purchased for €30,000 and swapped into €20,000 of native USDC would acknowledge a €10,000 loss. The USDC would obtain €20,000 of foundation.
If that USDC have been later exchanged into Bitcoin and not using a money balancing fee, the swap would retain deferral as a result of Bitcoin is exterior the acquired e-money-token exception. It might carry the €20,000 foundation into Bitcoin. A subsequent taxable Bitcoin sale for €30,000 would acknowledge a €10,000 acquire. Assume no charges, different token swimming pools, money changes or different positive factors and losses.
These quantities might offset if realized in the identical tax yr. If the web loss arose in a single yr and the acquire in a later yr, the sooner loss wouldn’t shelter that later acquire beneath the present rule. Recognition in several years can subsequently change the taxable consequence even when the transaction sequence returns the holding to its authentic worth.
The reporting trade-off follows from the identical mechanics. Asset-specific foundation would take away the portfolio-wide allocation method for brand spanking new disposals, however traders would wish to protect acquisition proof, weighted averages and the premise carried or reset via swaps. For older holdings, the proposed allocation route would additionally require a Dec. 31 valuation and a whole-portfolio choice that the textual content makes irrevocable.
The following legislative check stays forward. The 2027 finances file, checked Oct. 12, lists Nationwide Meeting plenary dialogue for Oct. 13.
The put up France’s tax proposal would tax Bitcoin-to-USDC swaps earlier than traders money out appeared first on CryptoSlate.