



Coinbase’s transfer to Texas modified the rule a shareholder needed to fulfill earlier than suing its administrators over alleged conduct from the corporate’s Delaware years. In an October 2 ruling, the Texas Enterprise Court docket dismissed Gary Guillaume’s spinoff motion as a result of he had not first demanded that Coinbase take motion on the claims.
The dismissal was with out prejudice, and the courtroom didn’t determine whether or not the alleged misconduct occurred. Its consequential discovering involved who might pursue claims belonging to Coinbase: Texas’s demand requirement utilized to the shareholder’s authority to sue, despite the fact that the courtroom assumed with out deciding that Delaware legislation ruled the underlying claims.
On October 9, Coinbase CEO Brian Armstrong praised the precedent as encouraging extra firms to include in Texas and thanked Greg Abbott. That endorsement got here every week after Choose Andrea Ok. Bouressa signed the order. The instant lesson for public shareholders is that the legislation governing an organization’s previous conduct and the legislation governing their capacity to problem it could possibly diverge after reincorporation.
Stand With Crypto's 4 million registered advocates couldn't get the CLARITY Act through the Senate
Why older claims confronted Texas’s demand rule
A spinoff motion lets a shareholder pursue a declare on the company’s behalf. The declare belongs to the corporate, and the shareholder seeks to train authority ordinarily held by its board. That distinction explains why the primary dispute right here involved permission to carry the motion relatively than the administrators’ alleged wrongdoing.
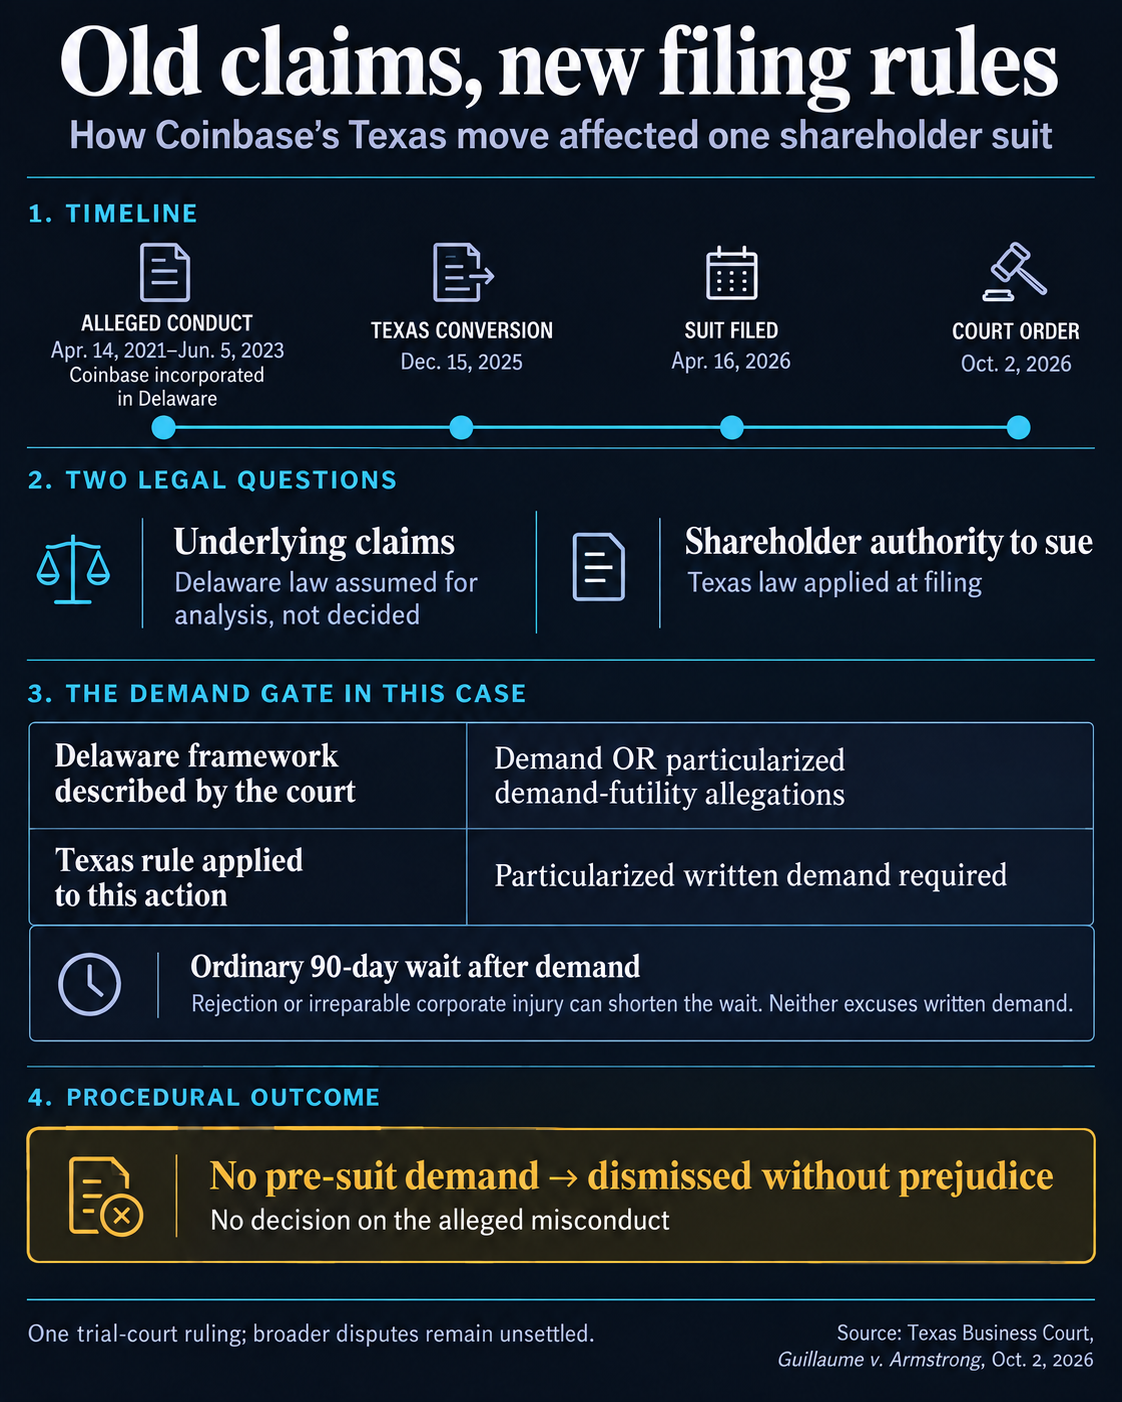
The events agreed that Guillaume filed his go well with on April 16, 2026, alleging misconduct between April 14, 2021, and June 5, 2023. Coinbase was included in Delaware throughout that ancient times. Its Texas conversion turned efficient on December 15, 2025, a number of months earlier than the go well with was filed.
Below the Delaware framework described within the opinion, a spinoff plaintiff could make a requirement or plead that doing so could be futile. Futility requires particularized allegations about particular person administrators, inspecting whether or not they acquired a cloth private profit, face a considerable probability of legal responsibility, or lack independence from somebody who benefited or faces such legal responsibility. At the very least half the related board should fulfill the check.
Guillaume tried that route. He didn’t make a pre-suit demand.
For this motion involving a public firm, Texas required a particularized written demand figuring out the disputed conduct and requesting appropriate company motion. The October 2 opinion described an odd 90-day wait after demand, with spinoff proceedings permitted from the 91st day. Company rejection of the demand or irreparable damage to the company can shorten the ready interval. Each exceptions go away the written-demand requirement in place.
Guillaume’s futility allegations couldn’t substitute for the written request Texas required. The lacking demand was sufficient to finish this motion earlier than the courtroom reached its deserves.
Guillaume argued that Delaware legislation ought to apply as a result of the claims arose earlier than Coinbase’s Texas transfer. Bouressa accepted that premise in regards to the underlying claims for functions of the evaluation, with out resolving it.
She then thought of a separate query: which state’s legislation ruled the shareholder’s authority to file these claims for Coinbase?
The courtroom’s reply turned on the corporate’s incorporation when the shareholder exercised that authority. A company declare can come up underneath one state’s legislation, whereas a later effort to pursue it derivatively is ruled by one other state’s guidelines. The opinion reasoned {that a} shareholder doesn’t purchase a vested proper, when a company declare arises, to carry it personally on the company’s behalf at some later date.
That reasoning offers reincorporation penalties past future board choices. On this case, the December 2025 conversion affected the route for difficult alleged conduct relationship again to 2021.
Coinbase’s conversion disclosures equipped Guillaume with one other argument. He relied on language preserving eligible shareholders’ standing and talent to carry spinoff claims regarding earlier conduct, topic to continued possession.
The opinion’s therapy of that language was narrower than Guillaume’s interpretation. The courtroom mentioned it didn’t promise that Delaware legislation would proceed to manipulate shareholder authority after conversion. The disclosures additionally expressly mentioned Texas legislation would govern Coinbase’s affairs following the transfer.
Bouressa additional discovered that Guillaume supplied no argument or proof exhibiting how shedding the choice to plead demand futility adversely affected his capacity to sue. He had not proven that making a requirement was inconceivable, irreparably dangerous or prejudicial, or that the futility possibility gave him a specific benefit.
The courtroom additionally discovered no proof that Coinbase had efficiently contracted across the Texas requirement.
SEC pays $150,000 as Coinbase-backed Freedom Of Information Act settlement releases two withheld documents
Concentrated votes, a unique accountability route
The governance backdrop makes that distinction matter. Coinbase’s November 2025 info assertion mentioned the Armstrong- and Fred Ehrsam-associated consenting group held roughly 78.40% of voting energy on the October 31, 2025 file date. The group accepted the conversion by written consent on November 4.
Coinbase mentioned a committee of Christa Davies and Paul Clement, whom the board discovered impartial and disinterested, evaluated Delaware, Nevada and Texas earlier than recommending Texas. The board unanimously accepted the transfer.
The corporate cited larger litigation predictability, potential financial savings on protection prices, indemnification and insurance coverage, and Texas’s crypto-friendly atmosphere.
The consent determine describes approval in 2025. In its April 24, 2026 proxy, Coinbase reported March 31 voting-power figures of 49.6% for Armstrong, 18.9% for individually listed Armstrong-associated entities and trusts with an impartial trustee, and 10.6% for Ehrsam. The figures use SEC beneficial-ownership guidelines, together with qualifying choices. Class B shares carry 20 votes every, in contrast with one for Class A.
Coinbase’s February 2026 annual submitting described Armstrong and the impartial trustee collectively as capable of train majority voting rights. Its July 30 quarterly submitting reported no materials adjustments to the annual danger elements, with out supplying a brand new particular person voting-power proportion.
Funds are buying crypto stocks. Are they exposed to less risk — or more?
The put up Coinbase’s Texas transfer will get a shareholder go well with dismissed over Delaware-era claims appeared first on CryptoSlate.