



European USDC holders looking for {dollars} from Circle might have to attend if reserves can’t transfer between its French and U.S. issuers, even whereas retaining their declare to a greenback. Circle’s present European redemption coverage permits non permanent delays throughout failed reserve rebalancing, exposing a cash-access boundary inside a token that’s interchangeable worldwide.
That boundary issues as Circle presses Europe to protect cross-border co-issuance. Its Oct. 1 response to the European Fee’s MiCA overview argues that the construction retains international stablecoin liquidity inside Europe’s regulatory perimeter. The present phrases present what can occur when the reserve transfers supporting that construction can’t be accomplished.
The controls distinguish approved crypto service suppliers from different European Financial Space holders. Suppliers might face a redemption cap primarily based on beforehand reported holdings; different holders might face checks establishing that their holdings originated throughout the EEA earlier than the stress started.
These are contingency provisions. The general public paperwork reviewed don’t set up an energetic reserve-transfer failure or an imposed reserve-stress redemption restriction as of Oct. 4. They however qualify what European customers can assume about entry to issuer money throughout stress.
Below Circle’s MiCA redemption coverage, Circle France, formally Circle Web Monetary Europe SAS, handles redemption for USDC holders established within the EEA. Holders established exterior the EEA train their redemption rights with Circle Web Monetary, LLC below its personal settlement.
The coverage says that allocation preserves the proper to redemption at par below Article 49 of MiCA. For a holder, nevertheless, the quantity of the declare and the timing of the cost are separate questions.
Circle’s present EEA Mint phrases make the timing distinction express. A buyer might submit a redemption request at any time, however execution stays topic to authorized, regulatory, compliance, prudential, liquidity and operational situations.
Fed guarantees 2-day stablecoin payouts, but $76B remains blocked
The redemption coverage is marked Sept. 15, 2026, and the USDC white paper lists an modification on that date.
Two methods redemption may be deferred
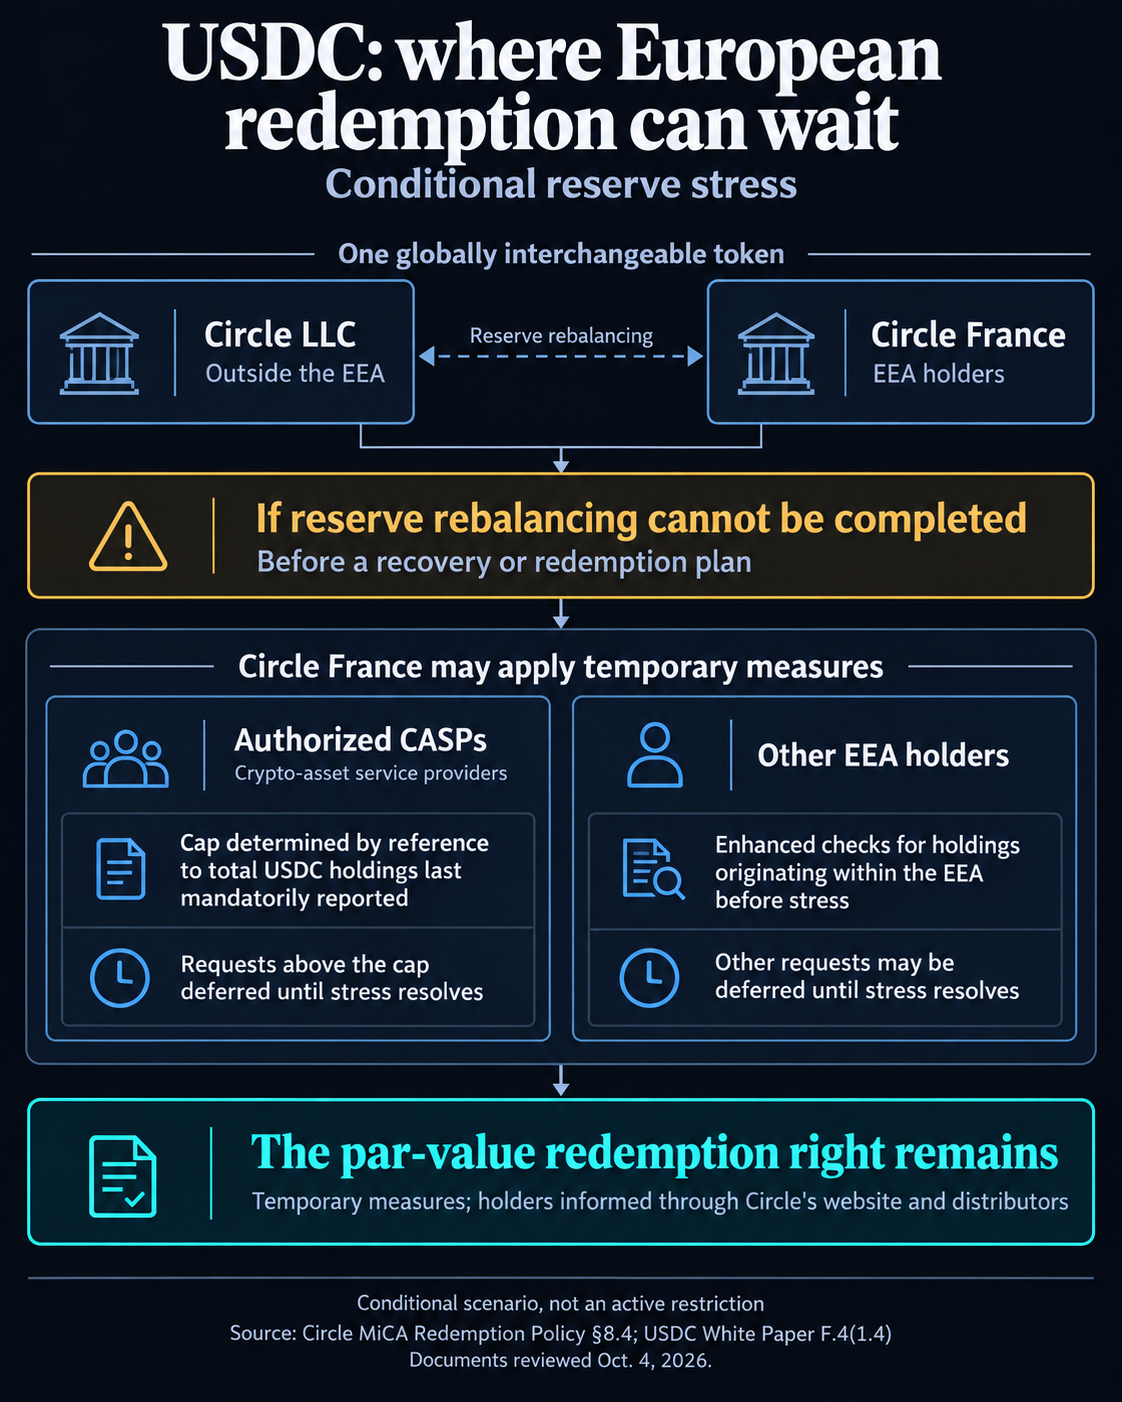
Part 8.4 of the redemption coverage defines a Stress Occasion as a interval when USDC reserves can’t be rebalanced between Circle France and Circle LLC, earlier than a Restoration Plan or Redemption Plan is activated. Throughout that interval, Circle can modify the processing and order of redemption requests, together with deferring execution past extraordinary coverage timing.
The USDC white paper, in Part F.4(1.4), units out the holder-specific measures:
- Licensed crypto-asset service suppliers: Circle France might impose a short lived most redemption restrict referenced to the supplier’s whole USDC holdings as final reported below its necessary reporting obligation. Requests above it could be deferred till the stress is resolved.
- Different EEA holders: Circle France might briefly limit redemption to holdings that enhanced checks clearly establish as originating from USDC holdings throughout the EEA earlier than stress. Different requests may very well be deferred till decision.
Circle describes the changes as non permanent and non-discriminatory, preserving redemption at par. Its coverage offers for informing holders by means of its web site and distributing suppliers. If rebalancing just isn’t restored, redemption is managed below the restoration or redemption preparations.
The controls can subsequently have an effect on each an middleman looking for issuer money and an EEA holder looking for to redeem straight. Having the ability to obtain USDC throughout stress wouldn’t, by itself, set up {that a} non-provider’s new holdings fulfill the pre-stress EEA situation.
A secondary-market sale might nonetheless present an instantaneous exit whereas issuer redemption waits, if a purchaser or middleman is prepared to pay. The conditional cash-flow implication is that one other celebration should provide the money earlier than Circle settles. A purchaser might buy the tokens outright utilizing its personal liquidity; no mortgage would essentially be concerned.
An trade promising to pay earlier than Circle would rely by itself money preparations and accessible liquidity. The token’s persevering with par-value declare doesn’t routinely fund that cost. An middleman selecting to advance money would tackle the timing hole till it might redeem or in any other case get rid of the tokens.
The reviewed paperwork establish no named middleman dedication to supply unrestricted quick cash-outs below this reserve-stress situation, nor an accessible stress-market bid or financing value. A sale would rely upon a prepared purchaser and the phrases provided.
Proposed stablecoin rules might guarantee your dollar while making you wait a week to spend it
World backing disclosures reply a special query. Circle’s transparency web page describes reserve disclosures and month-to-month third-party assurance of backing.
The white paper describes a French minimal reserve requirement equal to EEA USDC holdings and an inter-issuer rebalancing process. That requirement has to accommodate adjustments in the place tokens are held. The paper expressly identifies the danger that Circle LLC can’t rebalance reserves when holdings and redemption requests shift towards the EEA.
The reserve-transfer check behind Circle’s coverage case
Circle’s Oct. 1 response recommends preserving multi-issuance and formalizing safeguards, together with dynamic rebalancing between international and EU-specific reserves. It argues that proscribing the construction would push stablecoin use towards offshore suppliers and out of doors MiCA’s protections.
EU central banks attack MiCA rules and stablecoin runs are blamed
Europe’s systemic-risk watchdog has superior a special place. In its 2025 suggestion on third-country multi-issuer stablecoins, the European Systemic Danger Board requested the Fee to interpret the prevailing MiCA framework as not allowing such schemes. If the Fee thought-about in any other case, it really useful a devoted framework with safeguards.
Adopted Sept. 25, 2025, the advice additionally referred to as for assessing limitations to order mobility and acquiring proof that supporting establishments can promptly promote property, switch funds throughout borders and retain entry to cost techniques.
Circle’s phrases present why these operational questions matter to holders. Rebalancing is a safeguard when money can transfer to the issuer dealing with redemption requests. When it can’t, non permanent restrictions can shift the wait onto service suppliers and different EEA holders, even whereas the par-value proper continues.
The sensible checks are subsequently reserve-transfer readiness, the therapy of holders’ requests and any middleman’s precise cash-out enterprise. Circle’s coverage case depends upon holding international liquidity accessible in Europe; its present redemption phrases acknowledge the situations below which European entry to that liquidity might gradual.
The submit Circle can delay European USDC redemptions if reserves can’t cross borders appeared first on CryptoSlate.