



Cardano’s proposed programmable-token customary might let a freeze on one asset briefly block unrelated tokens held in the identical transaction output.
CIP-113, merged into Cardano’s foremost improvement-proposal repository on Sept. 29, is designed so as to add issuer-controlled switch guidelines to native property with out abandoning the community’s prolonged unspent transaction output, or eUTXO, mannequin.
The Cardano Basis has positioned programmable tokens as infrastructure for regulated monetary property, together with stablecoins, securities and real-world property which will require switch restrictions, freezes and different compliance controls.
The framework might due to this fact broaden Cardano’s enchantment to institutional issuers whereas introducing new dependencies for wallets and DeFi functions when a number of property share the identical output.
Nonetheless, the milestone stops wanting full activation. CIP-113’s official web page nonetheless lists the proposal as “Proposed,” with its path to Lively requiring issuance on Preview and mainnet, end-to-end testing and help from a broadly adopted pockets.
Nonetheless, Matteo Coppola, chief government officer of Fluid Tokens and a contributor to CIP-113, hailed the milestone, saying the merge adopted years of growth and places the framework in Cardano initiatives' fingers.
“This implies the official customary for programmable tokens on Cardano, together with securities, is out,” Coppola stated, including that contributors had labored to make it production-ready.
Compliance guidelines can spill throughout a shared output
That institutional flexibility comes with a structural complication: on Cardano, the principles governing one programmable token can have an effect on different property bundled alongside it.
Underneath the eUTXO mannequin, a transaction output can comprise a number of tokens in addition to ADA. Spending that output consumes it as a unit, so a restriction hooked up to 1 programmable asset can decide whether or not your entire transaction goes by.
If an output incorporates restricted token A, unrelated token B, and ADA, for instance, a freeze or denylist rule on A can stop the holder from spending that output to maneuver B. Neither B nor the ADA has been independently frozen, however each grow to be briefly inaccessible as a result of they share the identical output with A.
CIP-113 offers a approach to break that dependency by a restructuring mechanism often called “unfracking.”
The method permits one token coverage to be separated from the remainder of an output with out altering possession. If the transaction is permitted, A might be moved into its personal output whereas B stays in one other output managed by the identical holder. A stays restricted, whereas B is not topic to A’s switch rule on a subsequent spend.
Nonetheless, the holder doesn’t mechanically management the power to separate the property.
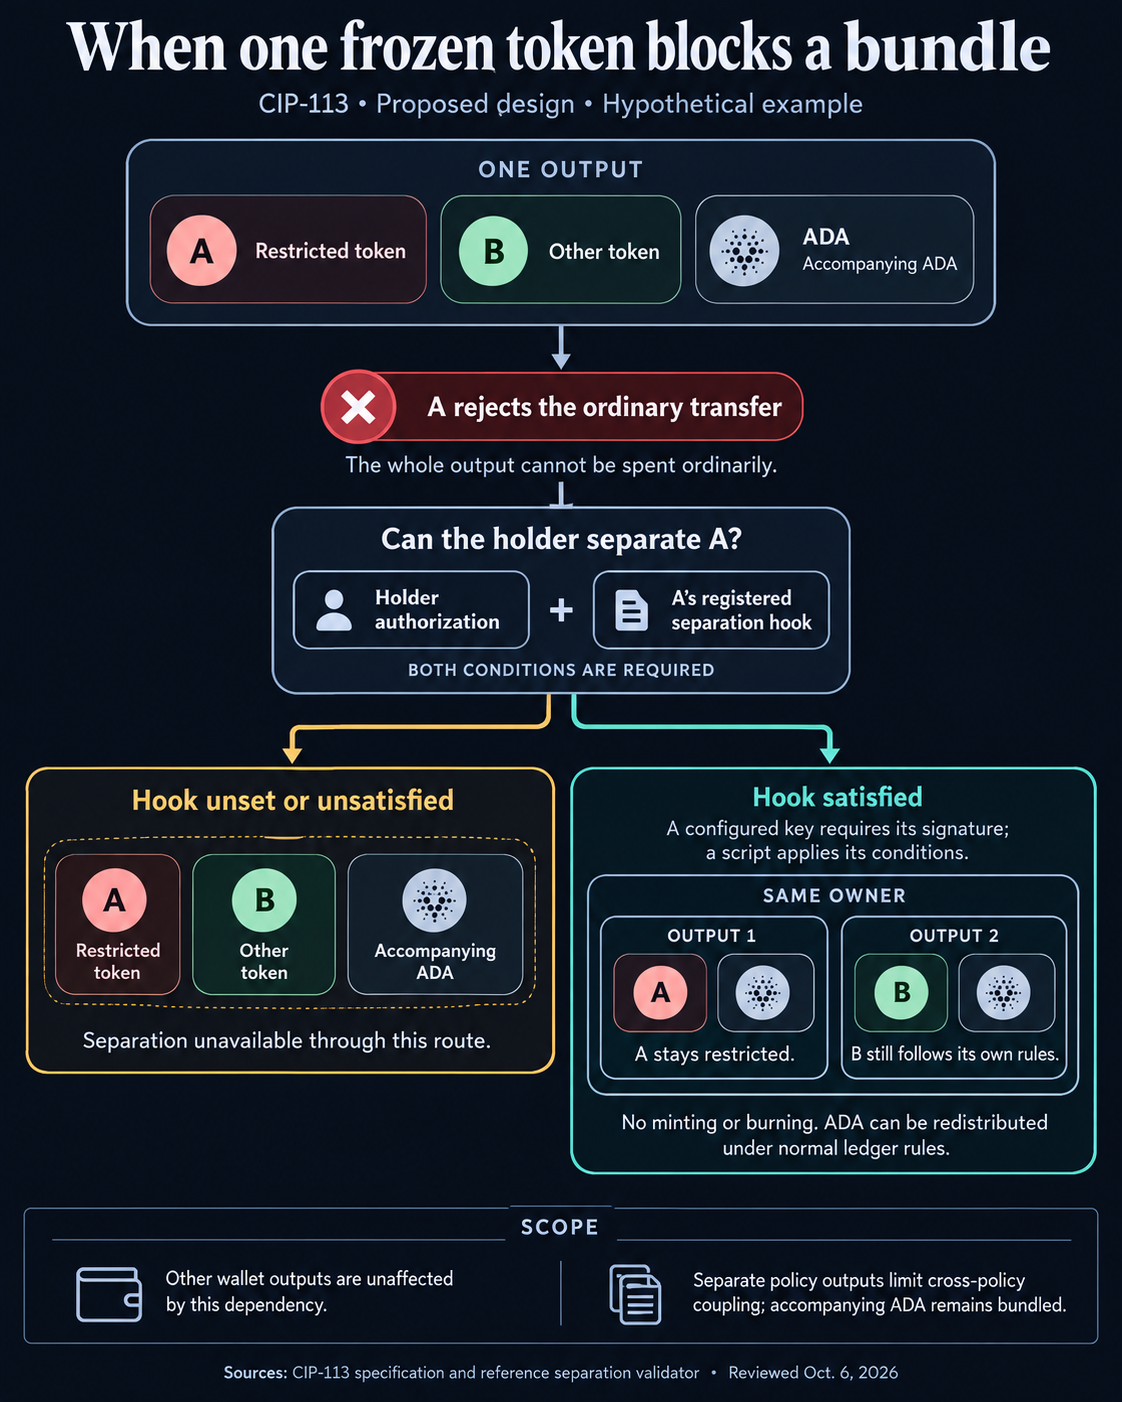
An unfracking transaction requires the holder’s authorization and should additionally fulfill the affected token’s registered separation guidelines. These guidelines can require a further signature, impose circumstances by a script, or block the restructuring route fully.
Which means a holder can not all the time free unrelated property just by signing a transaction. If A’s coverage doesn’t permit separation, B and the ADA sharing that output can stay inaccessible till the related circumstances change.
The proposal attracts a line between that type of blockage and seizure. A token issuer’s management over A doesn’t give it possession of B or different property in the identical output, and the reference implementation is designed to protect balances belonging to unrelated token insurance policies throughout licensed third-party actions.
Cardano to focus on tokenized institutional vaults as DeFi's retail focus fades
For wallets and DeFi functions, the sensible consequence is that asset possession alone might not decide speedy spendability. How tokens are grouped inside an output, and what separation permissions every coverage permits, can grow to be a part of the danger hooked up to holding or accepting them.
Wallets and DeFi protocols inherit the design danger
Avoiding that dependency for wallets and DeFi protocols might require altering how property are packaged earlier than any restriction is triggered.
The CIP-113 reference implementation describes single-policy outputs as the popular development, though the validator doesn’t require builders to make use of them. Protecting programmable property separate would cut back the danger that one issuer’s compliance motion prevents an unrelated token from shifting.
ADA stays uncovered to the identical constraint. Cardano outputs containing tokens additionally carry ADA, which means a number of the community’s native asset can grow to be briefly inaccessible when it shares an output with a restricted programmable token.
That provides complexity for wallets. A displayed stability might present what a consumer owns with out revealing what can instantly be spent. Purposes supporting CIP-113 may have to trace which insurance policies share an output, the permissions at present hooked up to every asset, and whether or not a blocked token might be separated.
For lending protocols, the problem turns into a collateral-management danger.
A DeFi platform accepting a programmable token would want to evaluate whether or not its issuer can freeze transfers, whether or not the protocol can authorize separation, and whether or not these controls might intrude with withdrawals or liquidations. A restriction arriving throughout a market downturn could possibly be notably consequential if a lender can not transfer collateral when it wants to shut an undersecured place.
These questions have gotten extra related as Cardano tries to increase its stablecoin and tokenized-asset market. USDCx, backed one-for-one by USDC by Circle’s xReserve infrastructure, has already added one other supply of greenback liquidity to the community.
CIP-113 might widen that market by giving potential issuers the compliance controls required for regulated stablecoins, securities, and different tokenized property whereas retaining Cardano’s native-asset structure.
The fee is that wallets and DeFi protocols might must deal with an asset’s permission construction as one other layer of economic danger.
Pockets builders might segregate programmable insurance policies by default, whereas lending protocols might impose decrease collateral values, tighter parameters, or reject tokens whose freeze and separation guidelines create uncertainty round liquidation.
That places the concentrate on the primary manufacturing integrations. As initiatives undertake CIP-113, their selections on output development and issuer permissions will assist decide whether or not regulated property can plug into Cardano’s DeFi markets cleanly or require protocols to cost the danger that compliance controls might prohibit entry to collateral when it’s wanted most.
The submit Cardano simply added the type of token controls Wall Road needs and DeFi might hate appeared first on CryptoSlate.