



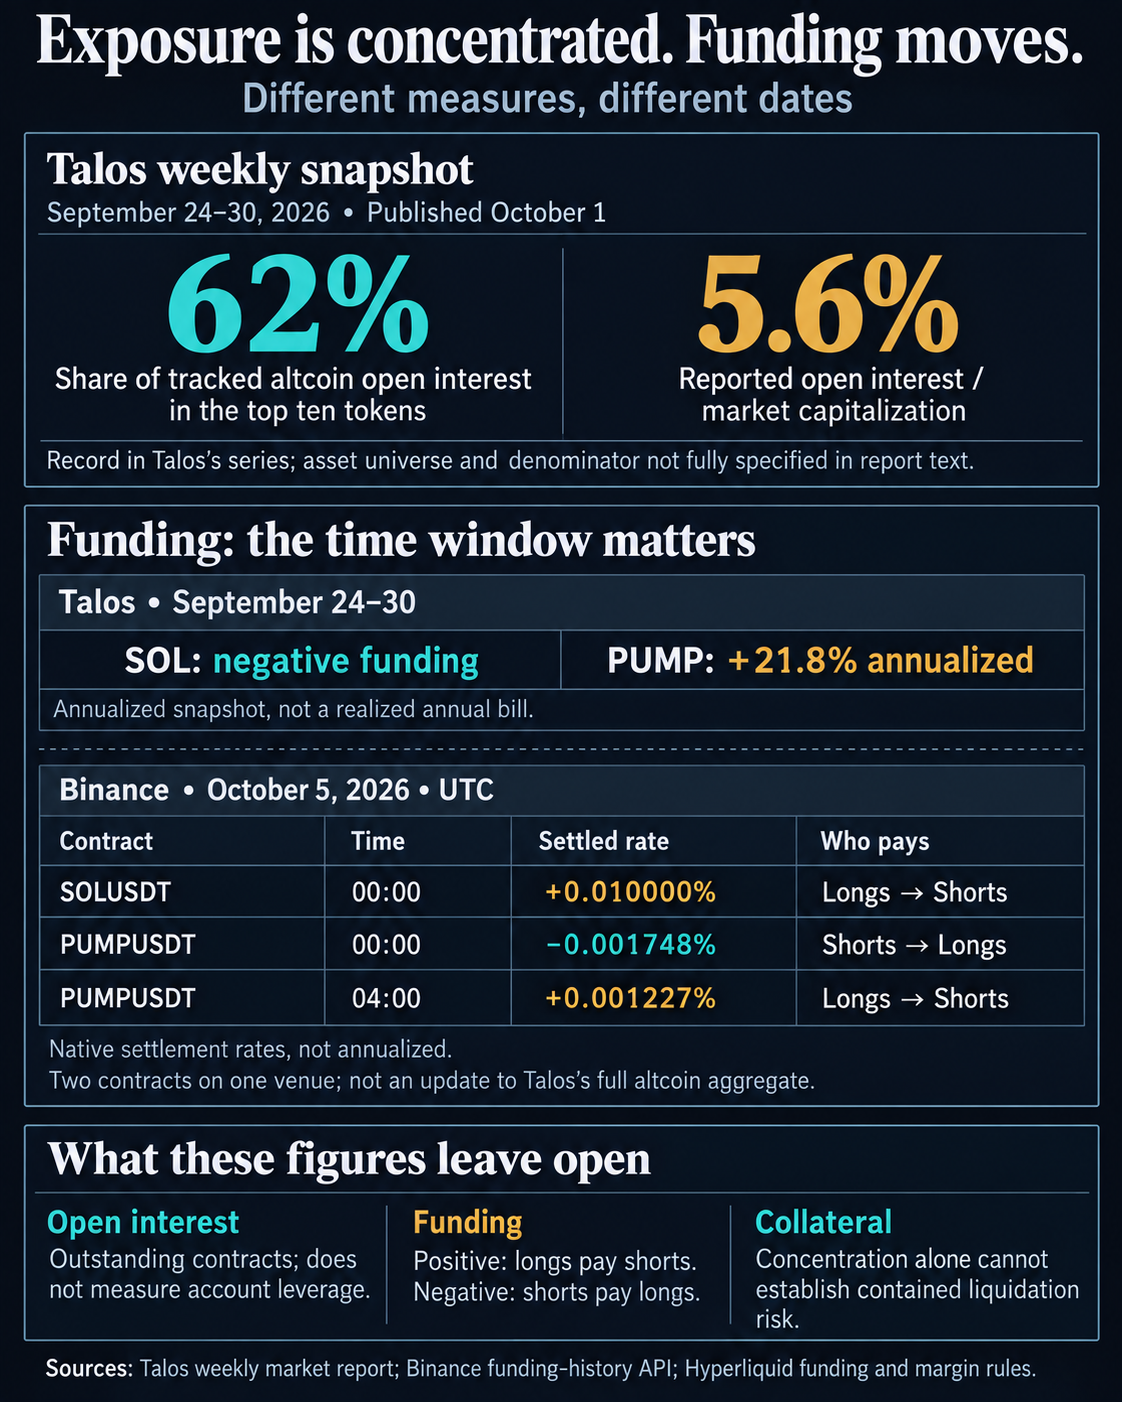
Ten tokens accounted for 62% of excellent altcoin futures publicity, generally known as open curiosity, in Talos’s weekly market report overlaying September 24–30, 2026. That concentrated publicity got here with completely different financing burdens: the report put SOL funding under zero whereas PUMP funding reached +21.8% annualized.
Revealed October 1, the market report additionally put altcoin open curiosity relative to market capitalization at 5.6%, a document in Talos’s sequence. For traders getting into the October buying and selling week, these numbers establish a concentrated derivatives footprint, whereas later Binance settlements present how shortly the price of holding a specific contract can change.
Funding strain can change inside hours
Perpetual futures use funding funds to assist preserve the contract value aligned with the underlying market. As Hyperliquid’s funding mechanics clarify, constructive charges switch cash from lengthy holders to quick holders. Detrimental charges reverse that course. A dealer’s financing burden subsequently is determined by the contract, facet and funding interval, even when two tokens each have substantial open curiosity.
The October 5 refresh covers two Binance contracts, somewhat than an identical replace to Talos’s altcoin combination. Their settled fee information, retrieved shortly after 04:20 UTC, present constructive SOL funding and a PUMP fee that modified signal inside 4 hours.
| Binance contract | Settlement, Oct. 5, 2026 (UTC) | Native settled funding fee | Paying facet |
|---|---|---|---|
| SOLUSDT | 00:00 | +0.010000% | Longs pay shorts |
| PUMPUSDT | 00:00 | -0.001748% | Shorts pay longs |
| PUMPUSDT | 04:00 | +0.001227% | Longs pay shorts |
Sources: Binance’s SOL settlements and PUMP settlements. Charges are native settlement percentages, not annualized charges.
SOL’s previous noticed fee, at 16:00 UTC on October 4, was additionally +0.010000%, eight hours earlier than the midnight fee. PUMP’s two noticed funds have been 4 hours aside.
PUMP’s midnight fee charged shorts; its 04:00 fee charged longs. The change illustrates a financing burden that may reverse whereas the underlying contract stays the identical. SOL’s constructive midnight fee additionally differs from the adverse funding described within the earlier Talos snapshot.
Annualization places periodic charges on a typical comparability foundation, somewhat than locking in a yr’s prices. Coin Metrics’ per-market documentation distinguishes the interval a fee applies to from the enter window used to calculate it. Hyperliquid settles hourly whereas dividing an eight-hour components into hourly funds.
Coin Metrics’ combination methodology weights normalized market charges by greenback open curiosity and scales longer combination durations linearly. Its day by day sequence is a boundary pattern somewhat than a day by day common. These definitions describe accessible metrics; they don’t establish the exact sequence or averaging window behind Talos’s +21.8% PUMP determine.
Bitcoin’s $87,000 rally just flipped from short squeeze to long risk
What the focus figures measure
Talos named SOL, XRP, HYPE and ZEC among the many largest markets in its top-ten group. The 62% share identifies the place publicity sat inside its tracked altcoin bucket. Establishing whether or not these tokens carried unusually giant derivatives positions for his or her dimension would require evaluating their publicity share with their share of market worth, utilizing the identical belongings and timestamp.
The report’s textual content leaves the historic beginning date and exact ETH remedy unspecified. These limits preserve the document tied to Talos’s sequence and forestall extending the 62% share right into a declare of disproportionate crowding.
The 5.6% ratio solutions a separate query: how giant excellent publicity was relative to the worth of the coated tokens. Coin Metrics’ capitalization definitions distinguish the worth of present issued provide, estimated circulating provide and free-float provide. These measures can assign completely different values to the identical token, particularly when provide sits in escrow or with strategic holders. The report’s textual content doesn’t establish which conference provides its denominator, so the 5.6% ought to stay a Talos-reported ratio somewhat than a common measure of altcoin leverage.
Beneath the usual open-interest definition, each excellent contract has a purchaser and a vendor, with one facet counted. Open curiosity subsequently describes unresolved contractual publicity.
Greenback values add one other distinction. Binance’s market-data fields separate excellent portions from their worth. A better greenback determine can mirror modifications in costs, portions or each. For a single linear contract with a matched value foundation and unchanged amount and provide definition, a value transfer can cancel out within the ratio. Throughout a basket, relative costs and constituents nonetheless matter.
The refreshed publicity observations are equally particular. Binance reported roughly $1.045 billion of SOLUSDT open-interest worth at 04:20 UTC on October 5. Its PUMPUSDT commentary was roughly $142.876 million at 04:15 UTC.
Altcoin spot volume nears 4x Bitcoin’s as ETF inflows shrink across five sessions
Concentrated positions can share collateral
Talos interpreted its publicity focus as limiting threat to comparatively few tokens. Its September 29 sector evaluation additionally characterised the rally as larger high quality.
Hyperliquid’s margin guidelines illustrate why the excellence issues. Cross margin shares collateral throughout eligible positions; remoted margin confines collateral to a place. With shared collateral, losses in a single holding can have an effect on the sources supporting one other. The scope of that sharing is determined by the account mode and markets concerned.
Its liquidation guidelines set off motion when account fairness falls under upkeep necessities. The venue initially makes an attempt to shut positions by means of the order e-book, with a backstop accessible underneath specified situations. Funding funds and losses on different cross-margin positions can have an effect on an account’s precise liquidation situations.
Your Bitcoin trade can now get liquidated because a stock crashed
An publicity share can’t reveal these account balances, liquidation distances or accessible e-book depth. It consequently can’t set up both {that a} cascade is inevitable or that threat stays contained inside the tokens with the most important open curiosity.
CryptoSlate’s earlier protection of ETF focus and altcoin spot turnover examined different dimensions of the rotation. Fund flows describe allocations, turnover describes buying and selling exercise, open curiosity describes excellent contracts, and funding describes periodic financing situations.
For traders assessing this market, the following helpful proof is a matched comparability of publicity and token worth, a sequence of settled funding funds, and the collateral and liquidity situations behind the positions. The reported 62% focus identifies a place to begin for that evaluation. The October 5 settlements present how shortly the financing burden at that start line can transfer.
The publish Ten tokens held 62% of altcoin futures publicity, however shared collateral can put different positions in danger appeared first on CryptoSlate.