



The European Securities and Markets Authority needs to increase Europe’s restrictions on non-compliant stablecoins past buying and selling to the providers that permit prospects maintain and transfer them. If adopted as proposed, the change would take away the choice of leaving such tokens with a licensed custodian after their buying and selling pairs disappear.
In its September 30, 2026 response to a evaluate of the EU’s Markets in Crypto-Belongings regulation (MiCA), ESMA asks the European Fee to ban each licensable crypto-asset service involving stablecoins that fail the regulation’s relevant necessities. Custody and transfers fall inside that service record. The consequence would attain current holders who’ve stopped buying and selling, in addition to prospects searching for to purchase.
That could be a additional step from the regulator’s January 2025 strategy, which mentioned mere custody and switch ought to stay attainable. It may give compliant tokens a wider benefit in European distribution, however neither a pressured conversion timetable nor a world demand shift follows from the proposal.
The permission left after delisting
ESMA’s January 17, 2025 assertion distinguished providers that supplied non-compliant stablecoins to the general public or admitted them to buying and selling from merely holding or transferring them. Platforms had been anticipated to cease making the tokens out there for buying and selling, and different providers needed to stop the place they constituted a proposal to the general public.
Beneath that earlier transition, acquisition restrictions had been anticipated by the top of January 2025, with non permanent sell-only providers by the top of the quarter.
For an investor, the custody distinction mattered. Shedding entry to a buying and selling pair didn’t essentially imply dropping the service that safeguarded an current stability or enabled its withdrawal. ESMA acknowledged that traders retaining these holdings may face worse execution circumstances, even whereas custody and switch remained attainable.
A historic instance exhibits the excellence. In its March 3, 2025 reporting, CryptoSlate mentioned Binance deliberate to take away 9 tokens’ buying and selling pairs for European Financial Space customers by March 31 whereas preserving deposits, withdrawals, conversions and custody out there. This was the alternate’s introduced strategy in March 2025.
How MiCA brings banks closer to controlling Europe’s stablecoin access
The September response would substitute the activity-by-activity distinction with a broader asset-compliance check. ESMA argues that the dearth of a transparent prohibition creates disparities between compliant and non-compliant issuers and facilitates regulatory arbitrage.
The attain comes from MiCA’s Article 3 definitions. Custody consists of safekeeping or controlling purchasers’ crypto-assets or their technique of entry, together with personal keys. Transfers cowl transferring belongings on a consumer’s behalf from one ledger handle or account to a different. Each are expressly listed providers, with Article 82 setting client-agreement necessities for transfers.
Supplier permissions are additionally separate from token compliance. Article 59 requires authorization as a crypto-asset service supplier, or qualifying permissions for specified monetary entities, and says authorizations should establish the providers permitted. A license for a supplier doesn’t by itself settle whether or not a specific stablecoin might be serviced.
An current holder would due to this fact not keep away from the proposed restriction by deciding by no means to commerce once more. If the wording grew to become legislation with out an exception, the custodian’s continued safekeeping would itself be lined.
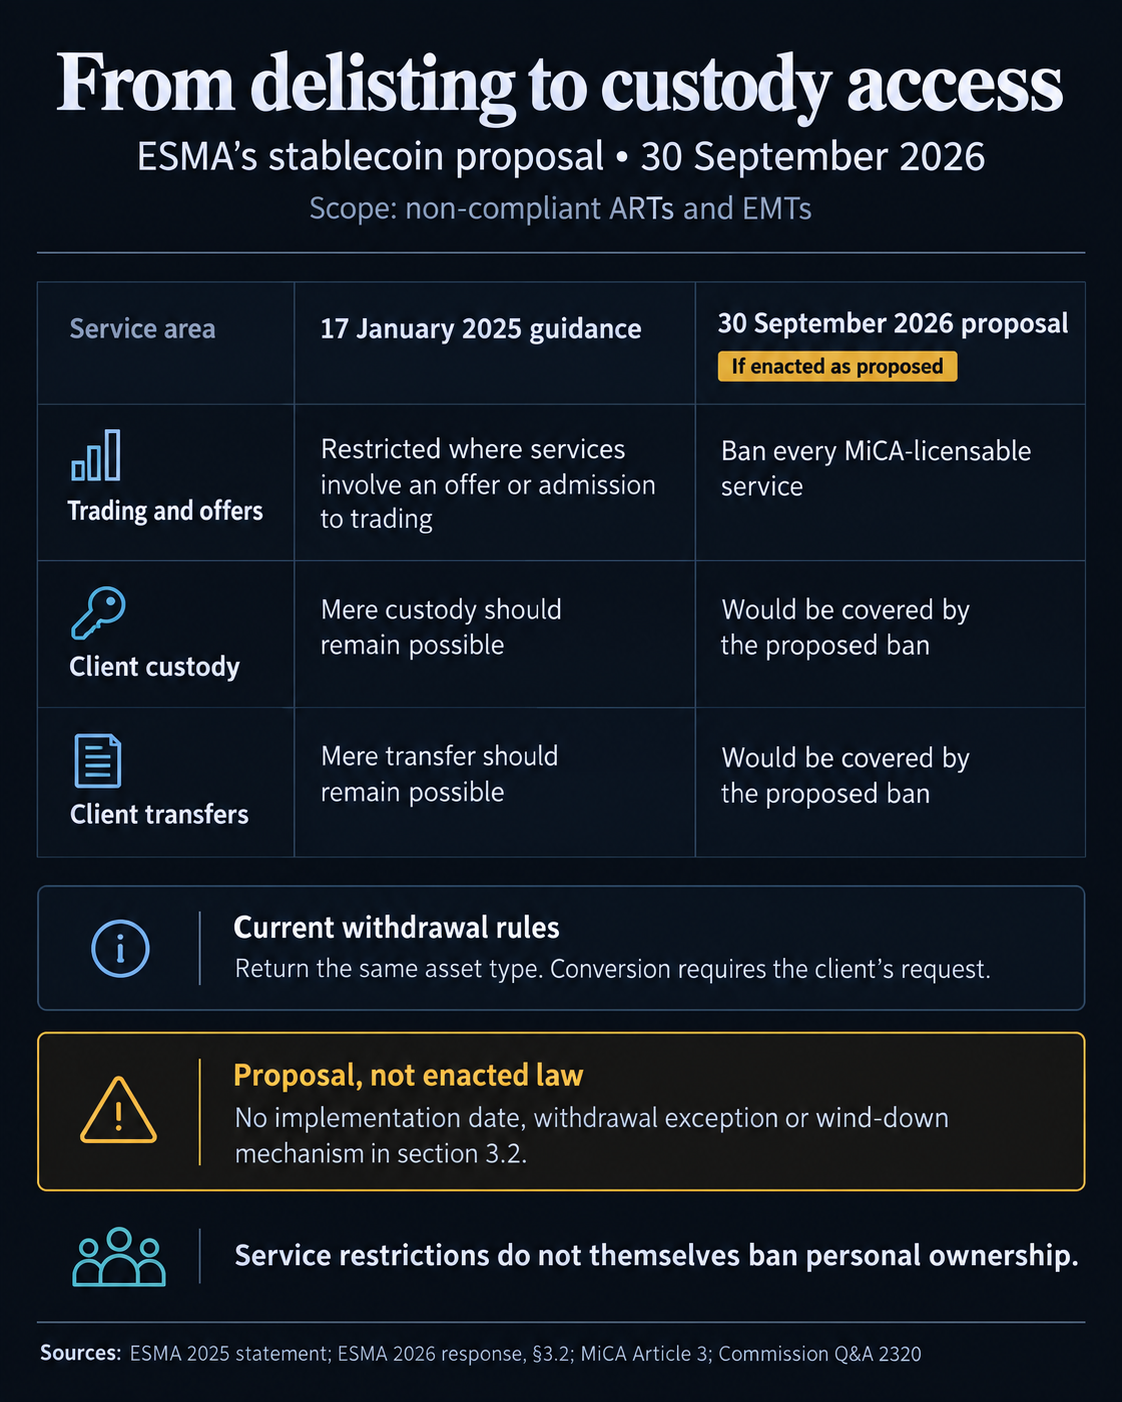
ESMA’s response is a coverage submission, not an enacted modification. The Fee’s session had a September 30 deadline, and its web page says the ensuing evaluate report might, if warranted, be accompanied by a legislative proposal.
Part 3.2 of ESMA’s submission offers no implementation date, withdrawal exception or wind-down mechanism. That omission issues as a result of ending custody requires a solution to return belongings {that a} supplier already controls, whereas the proposed prohibition additionally reaches switch providers.
Present custody guidelines present a related start line. Article 75 requires procedures to return purchasers’ crypto-assets or their technique of entry as quickly as attainable. Shopper belongings should even be segregated from the supplier’s personal holdings.
A solution from the European Fee through ESMA, dated February 18, 2026, additional says the belongings returned have to be the identical sort held when the consumer requests withdrawal. A supplier might provide conversion into fiat or one other crypto-asset, however the consumer should request it at withdrawal and the supplier will need to have permission for the extra service.
That current interpretation doesn’t settle how a future blanket service restriction would deal with exits. It does clarify why delisting, termination of custody and obligatory conversion can’t be handled as interchangeable outcomes. Legislators would want to resolve how any new prohibition suits the duty to return belongings.
The stablecoin proposal targets these skilled providers. It doesn’t itself ban private possession, order tokens frozen or prescribe obligatory conversion. A holder’s capacity to retain an asset and a licensed enterprise’s capacity to carry or transfer it for that buyer are completely different questions.
EU faces September 30 clock to decide future of DeFi loans
Buying and selling shares don’t measure custody publicity
The sooner delistings present how buying and selling can change at European-facing venues with out a comparable shift throughout a wider market.
In a July 2026 paper, Nicola Borri and Kirill Shakhnov look at buying and selling within the dollar-linked tokens USDT and USDC throughout 14 exchanges chosen from CoinMarketCap’s high 30 centralized venues. Their every day pair-volume knowledge from CryptoCompare run from January 1, 2024, by December 7, 2025.
The authors classify Bitstamp, Coinbase, Gemini and Kraken as “regulated-facing” as a result of their Similarweb EU viewers shares exceed 10%; all 4 even have US viewers shares above 10%. The opposite 10 venues are labeled as globally oriented, together with Binance regardless of its EEA delistings. The viewers proxy identifies neither particular person EU-resident trades nor a clear division of authorized publicity.
Across the examine’s April 1, 2025 occasion date, the authors estimate that USDC’s share of mixed USDT and USDC buying and selling rose by about six share factors on regulated-facing exchanges relative to international exchanges. The estimate covers a 30-day window and makes use of smoothed, detrended knowledge; it measures a relative buying and selling shift throughout venue teams.
The authors estimate USDT buying and selling quantity fell about 20% on regulated-facing exchanges relative to international venues, whereas the USDC-volume estimate was not statistically important. USDC gained share primarily as a result of USDT buying and selling contracted in that comparability, not as a result of the examine established a corresponding growth in USDC buying and selling.
Combination USDC-to-USDT trading-volume ratios throughout the pattern stayed practically flat across the occasion. That describes sampled alternate turnover, not worldwide demand or EU custodial balances. The authorized paperwork and examine present no complete for the holdings {that a} future custody restriction may have an effect on.
Europe's central banks want to scrap this stablecoin reserve safeguard
If the proposal grew to become legislation in its current type, compliant tokens may retain entry to regulated custody and switch channels that non-compliant tokens would lose. For purchasers who need a supplier to safeguard and transfer a dollar-linked stability, compliance may have an effect on the usefulness of that asset past the provision of a buying and selling pair.
The subsequent consequential textual content could be a legislative modification, notably its scope, software date and remedy of current balances. The way it reconciles an finish to custody with the return of purchasers’ belongings would decide whether or not and the way current holders should depart regulated providers.
The put up ESMA proposes ending EU custody and switch providers for non-compliant stablecoins appeared first on CryptoSlate.