



Open Jupiter, inform it you need to swap SOL for USDC, test the value, and press the button. From the consumer's perspective, there may be not far more to it.
So it's solely pure to imagine that Jupiter is the place the commerce occurs. In actuality, Jupiter is nearer to a search engine for liquidity. Its software program appears to be like throughout completely different locations prepared to take the opposite aspect of the commerce, compares what they’re providing, and sends the order towards one of the best route it may possibly discover. Its present system can select amongst odd decentralized exchanges, proprietary automated market makers, or propAMMs, and a request-for-quote community the place skilled market makers compete to cite a value.
The consumer sees one interface and one value, whereas beneath it a number of very completely different sorts of markets might be competing for a similar order.
So the individual promoting you USDC may not be one other consumer or a public pool funded by hundreds of strangers. It could possibly be knowledgeable buying and selling operation utilizing its personal cash and pricing software program, with no consumer-facing trade and no pool into which you’ll be able to deposit your personal tokens. You by no means see most of that equipment; you simply see the value that comes out of it.
A brand new evaluation from DWF Ventures estimates that propAMMs account for roughly 15% to 27% of day by day on-chain DEX quantity. For one a lot smaller nook of the market, SOL-to-stablecoin trades routed by way of Jupiter, DWF places their share above 90%.
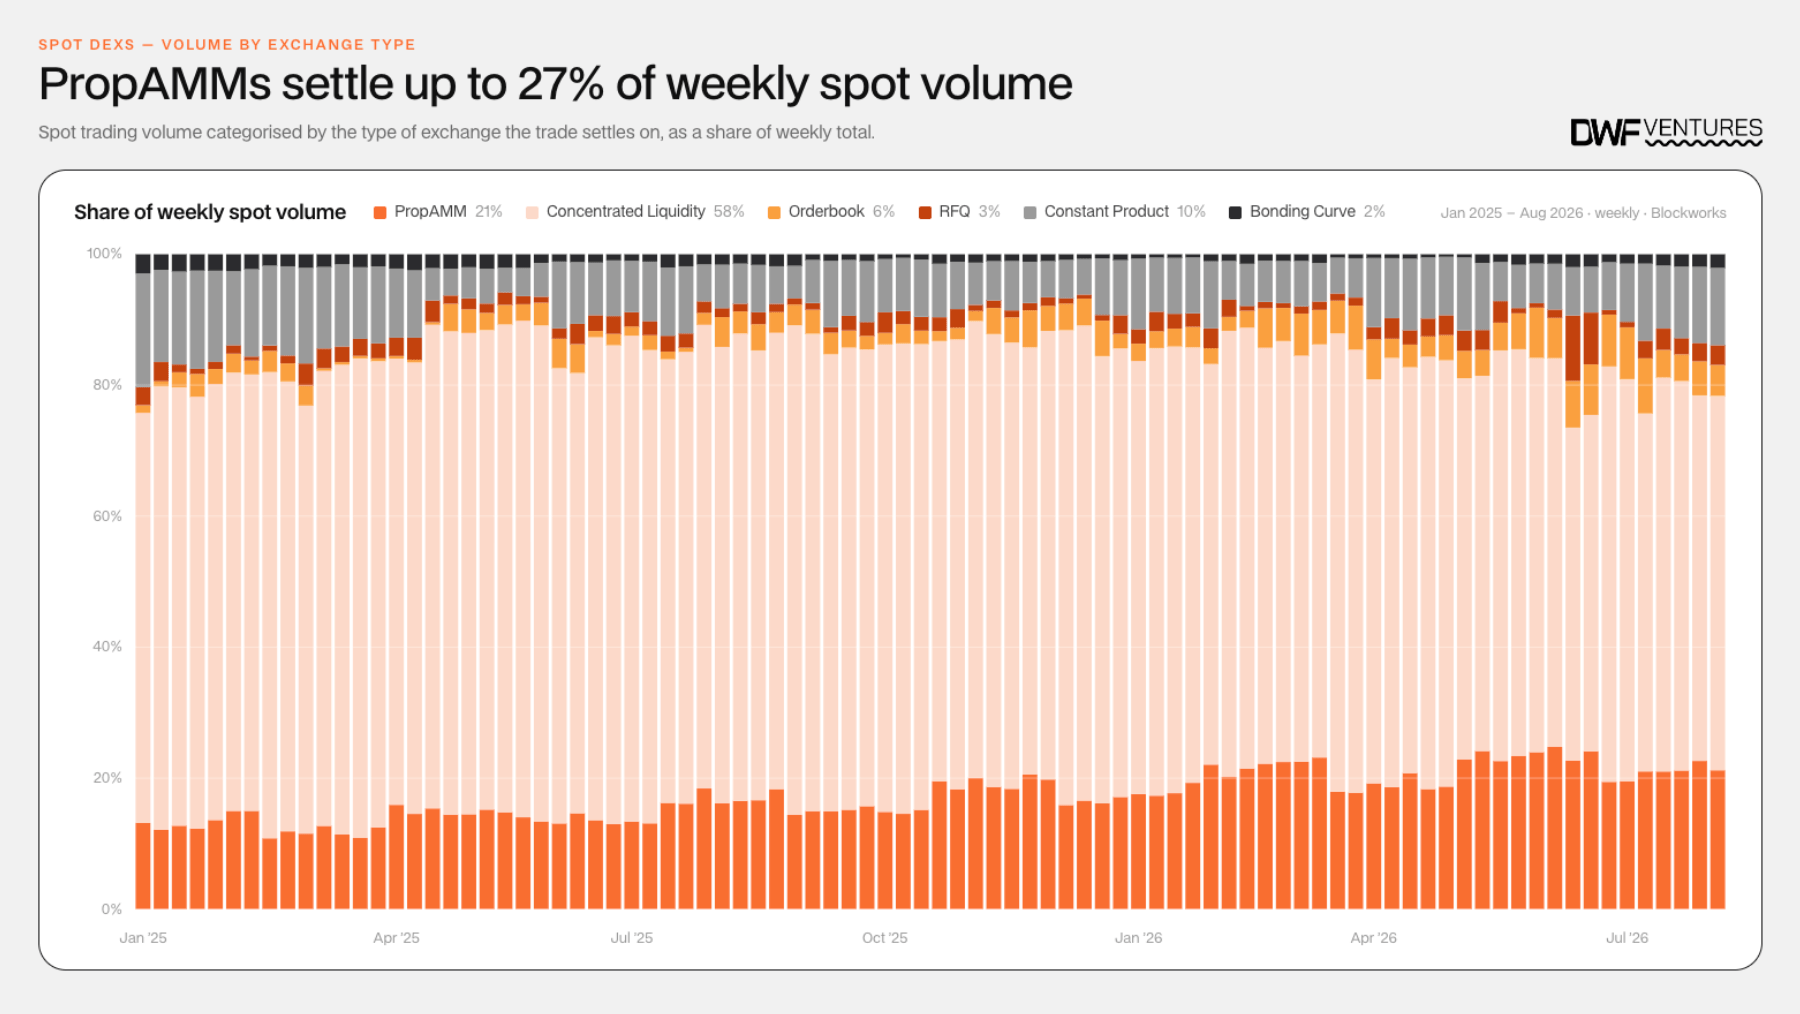
These numbers include an apparent caveat: DWF Ventures is a part of DWF Labs, which is itself a crypto market maker and investor. Nonetheless, the precise share offered right here is far much less fascinating than what the numbers describe. A type of buying and selling that hardly exists in most individuals's psychological mannequin of DeFi has turn into massive sufficient to form how a few of its busiest markets work.
That leaves crypto in a fairly unusual place proper now. The primary technology of decentralized exchanges was constructed round the concept that markets may turn into extra open by changing skilled sellers with public software program. Anybody may see the pool, put cash into it, and commerce in opposition to it in accordance with guidelines written into code. Now the skilled vendor is coming again, and in a few of the most liquid markets it appears to be very, excellent on the job.
That will already be an fascinating flip for DeFi. It turns into far more consequential when it's occurring on the identical second that Nasdaq, the London Inventory Alternate, Robinhood, and Kraken are engaged on placing conventional shares onto blockchain rails.
For years, finance has argued about whether or not Wall Road would transfer onto crypto's infrastructure. However now, a tougher query is beginning to kind behind it: what sort of market will probably be ready there when it does?
The sellers are again in enterprise
The unique automated market maker was considered one of DeFi's stranger innovations.
Think about a forex sales space with two piles of cash, besides there's no vendor behind the glass. One pile accommodates SOL and the opposite accommodates USDC. Software program connects the 2 utilizing a system. You set SOL in and obtain USDC. As SOL accumulates on one aspect and USDC disappears from the opposite, the system adjusts the value. Anybody also can contribute cash to the sales space and acquire a portion of the buying and selling charges.
That solved an unlimited drawback for early DeFi. A brand new market didn’t want to steer knowledgeable agency to maintain shopping for and promoting all day. It wanted tokens, a wise contract, and folks prepared to deposit capital, and the market may run itself.
Operating itself, although, isn't the identical factor as being good at buying and selling.
Suppose SOL is price $100 contained in the pool. Information hits, centralized exchanges transfer instantly, {and professional} merchants now worth SOL at $101. The pool doesn't discover by itself, however an arbitrageur does. They purchase the quickly low cost SOL and preserve shopping for till the pool's value catches up. The pool has discovered that SOL is price $101 by promoting SOL too cheaply.
Educational work calls the issue loss-versus-rebalancing. The terminology is much less necessary than what it means: a passive pool can repeatedly commerce at yesterday's value in opposition to individuals who already know at this time's value. That's a tolerable flaw when markets are calm, and buying and selling charges compensate the individuals offering liquidity. It turns into an costly drawback when costs are transferring shortly, and each stale quote is an invite for critical and sizable arbitrage.
A propAMM reverses the association. As an alternative of counting on hundreds of outsiders to deposit tokens, knowledgeable buying and selling agency provides its personal stock. As an alternative of ready for trades to tug a system towards the correct value, its non-public software program watches exterior markets and frequently modifications what it’s prepared to purchase or promote for. The transaction nonetheless settles on-chain, however the considering that produced the value occurs throughout the firm.
It's truly a lot nearer to an digital forex vendor put in inside a blockchain than to the vending-machine mannequin that outlined early DeFi.
It additionally explains why the phrase “proprietary” belongs within the identify. Solana's personal explainer says at this time's propAMMs are typically closed-source, their liquidity is just not open for odd public deposits, and getting included by an aggregator is a permissioned course of. Customers can confirm {that a} transaction occurred on-chain with out having the ability to examine the system that determined what value to supply or why one market maker obtained the order.
From the outdated DeFi worldview, that may sound like regression. However, from the attitude of any person making an attempt to swap SOL shortly and cheaply, the decision is far much less ideological.
Bounce Crypto examined roughly 20 million propAMM fills from March and in contrast them with costs obtainable throughout Binance, Coinbase, OKX, and Bybit. Its analysis discovered that the median SOL-USDC fill executed 0.72 foundation factors from its benchmark centralized-exchange midpoint, whereas 91.9% of fills have been cheaper than Bounce's estimate for the bottom institutional centralized-exchange payment tier.
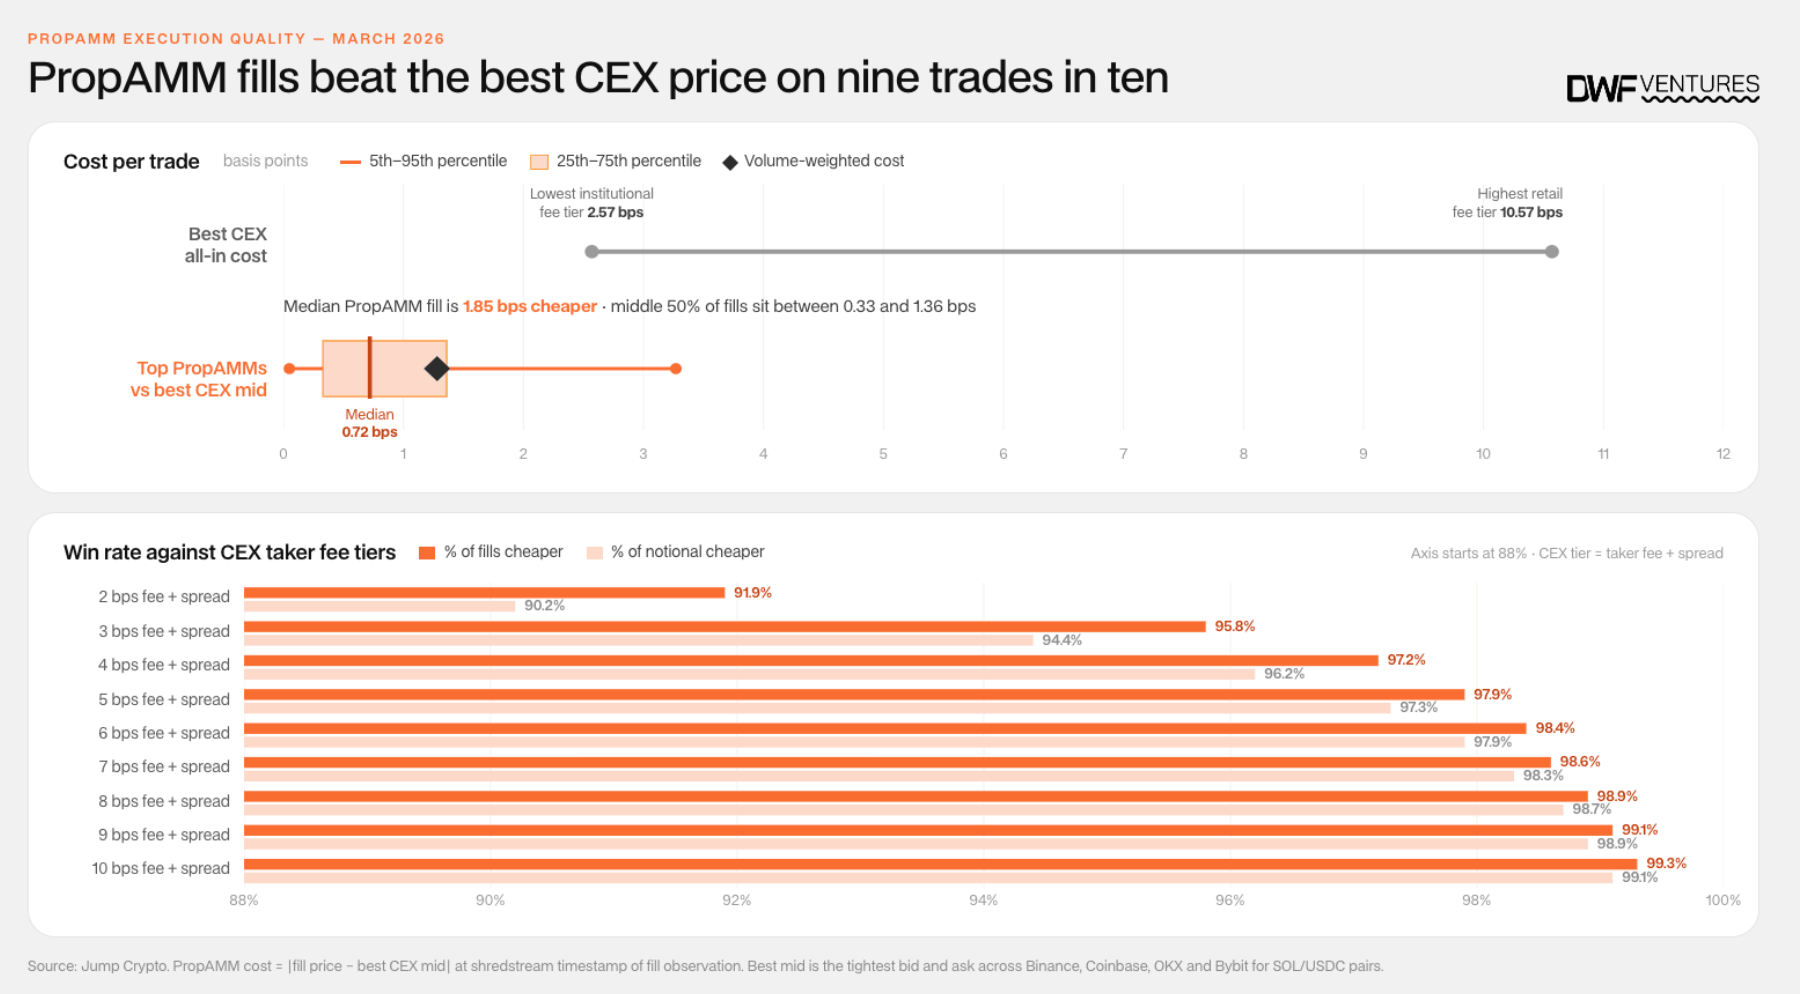
Bounce can also be a buying and selling agency with business publicity to this market construction, so its research has its personal incentives. Even so, the consequence helps clarify why these venues are successful orders. Routers ship them quantity as a result of, for sure trades, they’ll provide excellent execution.
Whereas it is a clear separation of each the mechanics and economics of decentralized buying and selling, it's additionally a cultural break with early DeFi. The primary model of DeFi handled openness as a part of the product itself. The pool was public, the code could possibly be inspected, liquidity got here from customers, and the route from capital to transaction was seen sufficient {that a} technically competent individual may comply with most of it.
The newer model asks a extra consumer-like query: if one other system provides you a greater value, how a lot of that equipment do you truly have to see? As soon as the reply turns into “not very a lot,” the trade begins to vanish behind the interface.
DeFi is popping exchanges into routers
Solana was significantly hospitable to this mannequin as a result of skilled market makers care obsessively about outdated costs. A agency providing SOL at $100 doesn't need that quote hanging round whereas the remainder of the world trades at $101. Each further second provides any person a possibility to commerce in opposition to the outdated value earlier than the agency can change it.
Ethereum nonetheless operates with 12-second slots. Solana, by comparability, reached its 300-millisecond goal on Aug. 28, which CryptoSlate examined by way of the economics of stale-price arbitrage. The networks construct and course of transactions in a different way, so the comparability is just not one-for-one, however the attraction is straightforward to grasp. Skilled market makers need to replace costs as typically and as cheaply as potential, and Solana's personal work on shorter slots explicitly factors to decrease stale-price publicity for liquidity suppliers and market makers.
You possibly can attain the identical vacation spot one other means, although. As an alternative of frequently publishing each value on-chain, a system can ask skilled corporations for costs elsewhere and put solely the successful commerce on-chain.
That's primarily what request-for-quote programs do. On 0x's RFQ community, an software asks skilled market makers for personal off-chain costs, compares these gives with odd public AMM liquidity, and returns whichever route gives the higher consequence. For extremely traded pairs comparable to USDC-WETH and WBTC-WETH, 0x says its RFQ liquidity beats AMM pricing about 52% of the time.
Jupiter is combining a number of variations of that on Solana. Public DEX liquidity, propAMMs, {and professional} quote programs all reside behind the identical interface, which implies the dealer now not has to decide on what sort of market to make use of earlier than making the commerce.
Which may be the deeper and extra necessary transition right here. Outdated DeFi successfully instructed the consumer: here’s a pool, now commerce in opposition to it. However new DeFi is beginning to say: inform me what you need, and I'll work out who ought to fill it.
Conventional finance already does this. When any person submits an order to purchase a inventory, the client often doesn't select the precise market middle or vendor that executes it: it's the dealer that routes the order. The SEC's fundamental rationalization of US fairness execution describes brokers selecting amongst exchanges, digital networks, market makers, and internalization relying on the place they’ll acquire one of the best obtainable execution.
PropAMMs aren't simply Wall Road darkish swimming pools transplanted onto Solana, and treating them that means would miss what makes the crypto model fascinating. Blockchain settlement is observable, so the property transfer throughout public infrastructure, and anybody can examine the ensuing transaction. What can stay non-public is the equipment round that transaction: the pricing mannequin, the stock choice, components of the route, and generally the identification of the agency competing for the commerce till execution happens.
That creates a unique definition of transparency. A monetary market can expose possession and settlement to public verification with out exposing each a part of value formation, and this distinction is turning into far more consequential because the property transferring by way of these programs cease being purely crypto property.
Wall Road is coming simply as DeFi modifications course
Nasdaq stated Thursday that its enterprise arm agreed to take a position $100 million in Payward, Kraken's mum or dad firm, whereas the 2 corporations proceed work on Nasdaq Fairness Tokens. Nasdaq expects the framework to launch within the second quarter of 2027 and plans to attach it with Payward's xStocks community.
The London Inventory Alternate is transferring in the identical course. On Sept. 1, LSEG introduced a partnership with Payward round tokenized public equities and stated it intends, topic to regulatory approval, to listing xStocks for buying and selling on its deliberate LSE 24 venue in 2027.
That is now not a hypothetical market measured in a handful of pilots. CryptoSlate has already tracked tokenized inventory buying and selling at crypto-scale volumes, whereas the tougher possession query has turn into its personal market-structure difficulty as a result of merchandise that resemble shares can include very completely different rights. Tokenized shares can seem like acquainted equities with out giving consumers the identical authorized place, and the infrastructure beneath them might be simply as unfamiliar.
Robinhood is an efficient instance of what that infrastructure could seem like in follow. Robinhood Chain has already turned tokenized shares into property that may flow into by way of permissionless crypto markets, however the skilled liquidity layer appears to be like a lot much less like an open AMM experiment. 0x says its Inventory Token implementation connects functions to skilled market makers by way of RFQ, with USDG as the first base pair and Tokka Labs as the first maker collaborating by way of that system.
That's the purpose the place the DWF report's hypothesis about real-world property turns into far more necessary than the report itself. Mature tokenized property don't must inherit the market design of early DeFi just because they choose a blockchain. Tokenized Apple shares have a deep reference market elsewhere, skilled corporations able to managing stock round them, and merchants who care about execution high quality. Placing that share on-chain received't out of the blue make a passive public pool the pure place to commerce it.
For years, the tokenization debate requested whether or not Wall Road's property would transfer onto crypto's rails. However a way more necessary query is showing behind it: after they get there, whose market construction will they use?
CryptoSlate has already seen the identical rigidity elsewhere in tokenized equities. Markets offered as a solution to take away monetary middlemen can nonetheless rely closely on outdated monetary infrastructure, together with the brokers and custodians holding the underlying shares. One dealer now handles the backing for a big share of tokenized equities. The propAMM transition factors in the identical broader course from the buying and selling aspect: blockchains can alter which components of finance are public with out making each middleman disappear.
The commerce is public, however the buying and selling desk isn’t
The best conclusion could be that DeFi spent years making an attempt to flee Wall Road after which rebuilt it anyway, however that's too easy. What crypto may very well be doing is separating two issues that have been as soon as handled as in the event that they needed to journey collectively: transparency of settlement and transparency of execution.
Blockchains can publicly set up {that a} commerce occurred, switch the property, and let these property transfer by way of programmable infrastructure with out requiring the market maker's pricing algorithm to be public. The settlement layer might be open whereas the execution layer accommodates non-public corporations competing with each other.
There's an financial purpose for doing this. Skilled market makers that may defend themselves from stale costs and merchants exploiting outdated quotes don't must construct these losses into each value they provide odd customers. Higher info and quicker repricing could make a non-public vendor cheaper to commerce in opposition to than a completely public pool.
The trade-off strikes some place else. If customers cease selecting exchanges and begin selecting routers, the router beneficial properties far more affect over the market. It decides which corporations are allowed to compete, which liquidity sources obtain an order, what info accompanies it, how quotes are in contrast, and the way transactions attain the blockchain.
Solana's personal propAMM explainer recognized a number of variations of this drawback. The code might be closed, inclusion by aggregators is permissioned, and customers can't at all times independently confirm why one market maker received when a number of provide equal costs. The blockchain can present the commerce that occurred with out displaying the total competitors that occurred earlier than it.
That turns into extra necessary as market making, routing, transaction supply, and block constructing start to the touch each other. Blockworks Analysis has examined the connection amongst HumidiFi, transaction-landing system Nozomi, and block builder Harmonic, all related to Temporal, and located durations when HumidiFi value updates reached Harmonic validators first far more typically than different setups. The benefit later disappeared.
The episode is extra fascinating as a preview of the subsequent DeFi market-structure debate than as an allegation: when a number of layers can affect execution, what precisely counts as finest execution on a blockchain?
Conventional finance has spent many years writing guidelines round variations of that drawback. Finest execution, order routing, market entry, quote precedence, and conflicts between brokers and sellers all exist as a result of the place the place an investor presses “Purchase” is barely the start of the transaction. DeFi is rediscovering a few of that complexity whereas rebuilding the system from completely different items.
The distinction is that some items that traditionally lived inside the identical monetary establishment can now be separated and positioned on public networks. That makes the market extra inspectable in some locations and fewer inspectable in others, which is a way more fascinating end result than merely declaring it roughly clear.
None of this implies the unique AMM is disappearing. Its weak spot can also be the explanation it would most likely survive.
Skilled market makers work finest after they have some thought what an asset is price. SOL has deep markets elsewhere; Apple has a inventory trade; Treasuries have a reference value. Buying and selling corporations can have a look at these markets, calculate a worth, maintain stock, and quote round it.
Now think about any person creates Token X at 3 a.m. There could also be no deep exterior market, no reliable reference value, and no skilled agency prepared to warehouse it. Earlier than anyone could make a classy market, the asset wants a market in any respect. Public AMMs don't have to know what Token X is price: somebody simply provides Token X and USDC, and buying and selling can start.
That's why the DWF knowledge is extra fascinating as proof of a sorting course of than as proof that one design is changing one other. Skilled liquidity works particularly nicely for established property with deep reference markets. Conventional AMMs retain their benefit within the lengthy tail, the place permissionless market creation is extra worthwhile than shaving fractions of a share level from execution.
Tokenized finance may divide alongside the identical line. Apple shares, Treasuries, SOL, ETH, and different closely traded property are pure territory for classy sellers competing behind routers. Belongings with out mature exterior markets should rely on public swimming pools prepared to commerce no matter anybody deposits.
Crypto started with a a lot grander cultural promise: software program would take away the monetary intermediary. However its buying and selling markets at the moment are producing a extra sophisticated reply. Some intermediaries have been merchandise of outdated infrastructure, whereas others existed as a result of any person nonetheless has to cost danger, maintain stock, and stand able to commerce.
Blockchain know-how doesn't must remove that function to remake the market round it. The rails might be public, settlement might be inspectable, property can transfer between functions as a substitute of being trapped inside one establishment, {and professional} sellers can compete over the identical order with out proudly owning the infrastructure beneath it. The individual urgent “Swap” could by no means know which one received.
The long run trade could also be a blockchain everybody can examine, wrapped round a buying and selling desk nearly no person can see.
The submit Why 90% of your DeFi trades are quietly being routed again to Wall Road market makers appeared first on CryptoSlate.